ONE CONNECT
Real-time Account Aggregation and A2A Payment Initiation for financial institutions
Integrate payment account data and initiate A2A payments via a single API. Built for regulated financial institutions.
Connect to European PSD2 Open Banking APIs and bring account aggregation and payment initiation directly into your digital banking experience.
New opportunities
Leveraging the power of Open Banking
The entry into application of PSD2 and therefore the advent of Open Banking - which started in 2018 - instantly created new opportunities for financial institutions in scope.
Besides having to expose their own APIs to enable TPPs to access payment account data - always with the data owner/end-user's consent - financial institutions can also leverage these APIs to offer a wide range of additional services.
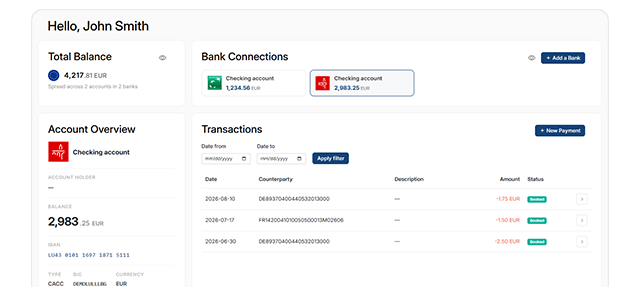
In a competitive environment, credit institutions can offer account aggregation services that give PSUs a unified view of their different payment accounts.
Moreover, PSD2 also enables innovative payment methods, and notably payment initiation, by leveraging the very same APIs.
Why LUXHUB for account aggregation & payment initiation
One single integration for a wide coverage
How it works
One API call, many use cases
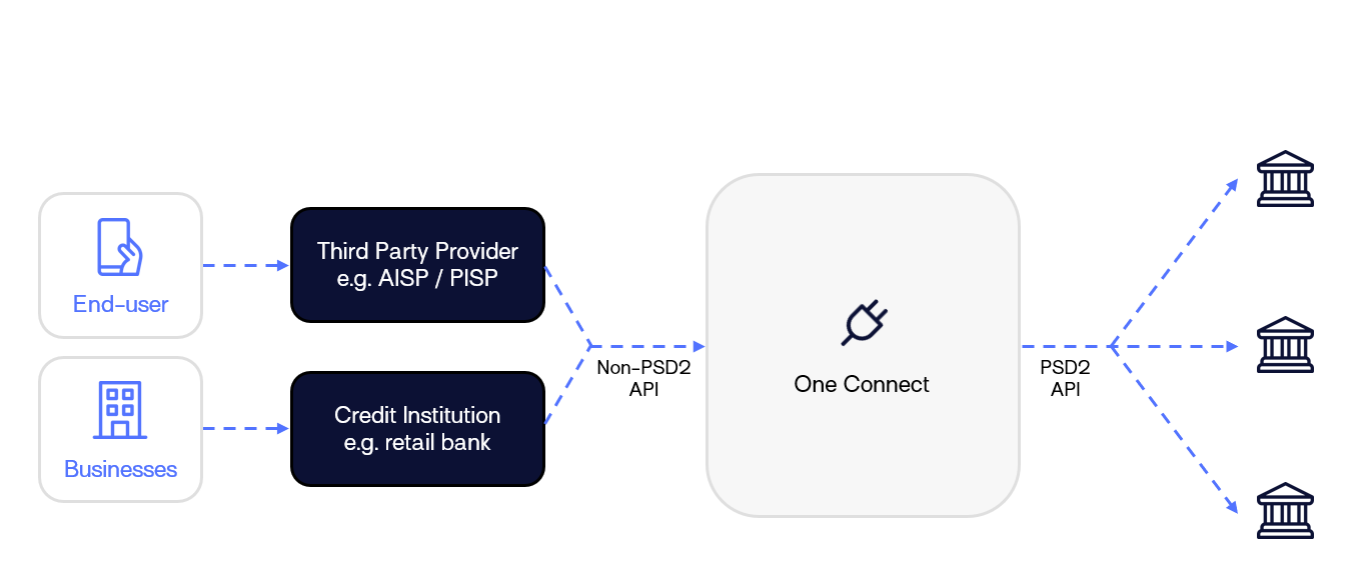
With One Connect, a single integration lets you provide your end clients with extensive payment account information and account-to-account payment solutions.
For financial institutions, numerous use cases can be developed around enriched financial data aggregation and payment initiation.
AIS & PIS
Capture payment accounts data,
empower customers with an additional payment method
PSD2 and the rise of Open Banking have created a wide range of opportunities for financial institutions, enabling them to deliver innovative value-added services to their customers.
Account Information Services
Integrate clean, segmented bank account information. Gain unique access to Luxembourg’s banking ecosystem and beyond. Build innovative solutions with real-time data.
Unified formats, flows and security profiles
Secure infrastructure, trusted by Luxembourg's biggest banks
Future-proof connections, with ongoing maintenance
Real-time balance information
Maintain ownership of your customer's flow, with full transparency
Payment Initiation Services
Provide fast, simple and secure payment methods to your customers: offer them a frictionless experience, from initiation to completion.
Aggregate all payments initiation methods
Offer the most cost-effective payments solution
Enable real-time, secure transactions
Own the value with a fully white-label solution
Compliant & secure
Supervised, certified, EU-hosted
(n° Z00000024)
FAQs
Questions teams ask about One Connect
All you need to know about LUXHUB's account aggregation and payment initiation solution.
An Account Information Service Provider (AISP) accesses payment account information, while a Payment Initiation Service Provider (PISP) initiates payments. Both are categories of third-party providers (TPPs) regulated under PSD2.
An AISP retrieves read-only data such as balances and transactions to deliver services like account aggregation or financial overviews. A PISP initiates payments from the customer's account on their behalf, without ever holding the customer's funds.
Both must be authorized or registered by a national competent authority and identify themselves to banks using eIDAS certificates. LUXHUB is itself supervised by the CSSF as both an AISP and a PISP.
Payment initiation is a PSD2 service that allows a licensed Payment Initiation Service Provider (PISP) to initiate a payment directly from a customer's bank account, with the customer's explicit consent.
The customer selects the account to be debited and authenticates with their own bank through Strong Customer Authentication (SCA). The payment is then executed as an account-to-account (A2A) transfer. Because funds move directly between bank accounts, payment initiation does not rely on card networks.
Payment initiation enables institutions to offer customers a simple and secure alternative to card payments and manually entered bank transfers.
Account aggregation is the consolidation of payment account information held at different banks into a single view, made even more convenient and secure by the Open Banking APIs introduced under PSD2.
With the customer's explicit consent, an Account Information Service Provider (AISP) can retrieve data such as balances and transaction histories from the customer's various Account Servicing Payment Service Providers (ASPSPs). This information can then be displayed in a single interface, such as a banking app.
For financial institutions, account aggregation makes it possible to offer customers a complete overview of their finances, without requiring them to switch between multiple banking apps.
LUXHUB One Connect is an Open Banking platform that enables regulated financial institutions to access account information and initiate account-to-account payments across multiple European banks through a single API.
One Connect connects to the PSD2 APIs of hundreds of banks across Europe and exposes them through one unified interface. Institutions can integrate real-time account aggregation and payment initiation directly into their own digital banking experience, without building and maintaining individual connections to each bank.
LUXHUB manages API maintenance, connectivity updates and operational monitoring, allowing institutions to focus on the services they deliver to their customers.
One Connect is designed for regulated financial institutions. These include credit institutions, such as retail banks, and licensed third-party providers acting as AISPs or PISPs.
Banks use One Connect to offer their customers a consolidated view of accounts held at other institutions, or to add payment initiation to their digital channels. Third-party providers use it to reach a broad network of European banks through a single integration, rather than connecting to each bank individually.
In both cases, the institution retains the relationship with its own end users, whether consumers or businesses.
One Connect provides access to hundreds of banks across Europe through a single integration, with coverage organized by market and continuously extended.
Coverage includes major banks in Luxembourg, Belgium, France, Germany and Portugal, as well as leading neobanks operating across Europe.
For the latest list of connected banks, institutions can contact LUXHUB.
One Connect unifies the formats, flows and security profiles of different bank APIs into a single, consistent API, regardless of the Open Banking standard each bank follows.
Across Europe, banks implement PSD2 through different standards, such as Berlin Group or STET, often with bank-specific variations. As a result, data structures, authentication flows and technical requirements can differ from one bank to another.
One Connect absorbs these differences on behalf of its clients. Institutions integrate once and receive harmonized data and payment flows from every connected bank.
Yes. One Connect is a white-label solution that allows institutions to integrate account aggregation and payment initiation into their own digital channels and user interface.
Account connection, consent collection and payment steps can all be embedded in the institution's own app or online banking. Customers then authenticate with the bank holding their account, as required by PSD2.
Institutions retain full ownership of the customer journey and user experience, with full transparency over the underlying flows.
Under PSD2, account information access and payment initiation always require the customer's explicit consent and Strong Customer Authentication (SCA) performed with the customer's own bank.
When a customer connects an account or initiates a payment through One Connect, the bank holding the account verifies the customer's identity using at least two independent authentication factors. For ongoing access to account information, PSD2 rules require customers to renew SCA at least every 180 days.
One Connect manages these bank-specific authentication flows through a single, consistent integration, helping institutions deliver a secure and compliant customer experience.
One Connect enables financial institutions to develop a wide range of services based on account aggregation and payment initiation.
With account aggregation, banks can give customers a consolidated view of all their accounts within a single banking app. They can also support personal finance management and budgeting tools, or offer business clients a centralized overview of their cash positions across banks. With payment initiation, institutions can enable account top-ups, transfers between a customer's own accounts at different banks, and direct account-to-account payments.
By combining both services, institutions can enrich their digital offering and strengthen engagement with their customers.
LUXHUB continuously maintains and updates One Connect's bank connections, so institutions do not need to monitor or adapt to API changes themselves.
Open Banking APIs evolve regularly through new versions, regulatory updates and changes to authentication flows. LUXHUB's connectivity specialists track these changes, update integrations and monitor connectivity and incidents on an ongoing basis. The integration layer also evolves alongside banks' APIs, covering both PSD2 APIs and premium APIs that go beyond the regulatory scope.
This keeps connections reliable and future-proof over time.
LUXHUB is supervised by the CSSF (Commission de Surveillance du Secteur Financier) in Luxembourg under number Z00000024, holding Support PFS status and authorization as an AISP and PISP under PSD2.
The company is ISO 27001 certified, and its solutions are hosted in the European Union, in Tier IV data centers located in Luxembourg. The solutions are also DORA-ready, in line with the requirements of the Digital Operational Resilience Act.
Together, these elements give financial institutions a secure, supervised and EU-hosted foundation for their Open Banking services.
Getting started with LUXHUB One Connect begins with a conversation with LUXHUB's connectivity specialists.
Financial institutions can request a consultation through the contact form on the One Connect product page, or contact LUXHUB directly at info[a]luxhub.com or +352 28 80 76.
Following an initial assessment of the institution's target markets, use cases and regulatory setup, LUXHUB defines the most suitable integration approach and onboarding timeline. LUXHUB then supports the institution from testing through ramp-up to full production.
FAQs
Questions teams ask about One Connect
All you need to know about account aggregation, payment initiation and LUXHUB's One Connect solution.
Verification of Payee (VOP) is a mandatory service introduced under the EU Instant Payments Regulation (IPR) requiring PSPs to verify that the name of a payment recipient matches the IBAN or account identifier provided by the payer before executing a credit transfer. VOP was introduced to address fraud and misdirected payments, cases where a payer is deceived or makes an error in entering payee account details, resulting in funds being sent to the wrong recipient.
VOP became mandatory for PSPs across several Eurozone countries on 9 October 2025, the first major deadline under the Instant Payments Regulation. From this date, PSPs offering Euro instant payment sending services must provide their customers acting as payers with a VOP check before authorising a credit transfer. Deadlines for non-Eurozone EU member states and for additional credit transfer types are phased in according to the IPR implementation timeline.
LUXHUB’s Payee Verification Platform is an EPC VOP Scheme-compliant solution designed to help PSPs across Europe comply with the Instant Payments Regulation’s Verification of Payee requirement.
The platform provides two complementary services: VOP Service Provision, which enables PSPs to expose and manage a real-time name-and-account-details verification service as the Responding PSP; and VOP Unified Access, which offers payer PSPs a single gateway to access VOP verification services made available to Requesting PSPs across Europe.
A Routing Verification Mechanism (RVM) is a technical provider that enables connectivity and inter-operability to payee PSPs to receive and respond to VOP verification requests in compliance with the EPC VOP Scheme. LUXHUB’s Payee Verification Platform acts as an EPC VOP Scheme-compliant RVM, handling all technical exchanges, name matching, and response generation required under the scheme on behalf of its client PSPs.
By acting as a RVM, LUXHUB enables multiple PSPs to comply without each building and maintaining their own individual infrastructure.
The Payee Verification Platform delivers two complementary services.
VOP Service Provision supports PSPs in their role as the account-holding institution: it exposes a secure, compliant real-time name and account-details matching service, manages account list import with built-in validation, stores data in encrypted siloed storage, and offers an API option fordirect access.
VOP Unified Access supports PSPs initiating credit transfers: it provides a single interface to verify any European recipient account, offers flexible integration endpoints (single/batch checks, web portal), and maintains direct partnerships with domestic and international schemes and hubs.
LUXHUB has developed a proprietary name matching algorithm specifically optimised for bank account naming conventions and the specific challenges of financial payment data, including variations in legal entity names, abbreviated names, accented characters, and transliteration issues. This algorithm goes beyond simple string comparison to deliver high-accuracy match, close match, and no-match responses while minimizing false positives that would unnecessarily disrupt legitimate payment flows.
Under the Instant Payments Regulation, VOP initially applies specifically to PSPs offering Euro instant payment sending services. However, the regulation’s scope is broader than instant payments alone, it applies to all types of credit transfers processed in euros, including standard (non-instant) SEPA Credit Transfers. This means PSPs must apply VOP checks not only when initiating instant payments but across their full range of euro credit transfer services, including bulk payments and corporate transactions.
VOP directly combats) fraud and misdirected payments by informing the payer before they authorise a transaction.In fraud scenarios, criminals typically deceive victims into sending payments to accounts controlled by fraudsters, often by impersonating suppliers, employers, or official bodies. VOP provides a real-time verification layer that flags mismatches, prompting the payer to investigate before the transfer is executed and irreversible.
The EPC (European Payments Council) VOP Scheme is a standardised pan-European framework defining the rules, technical standards, and operating procedures for Verification of Payee services across the SEPA zone. Compliance with the EPC VOP Scheme ensures interoperability between PSPs across EU member states allowing a French payer’s bank to query the VOP service of a German payee’s bank, for example. LUXHUB’s Payee Verification Platform is EPC VOP Scheme-compliant, ensuring its customers can connect with any PSP across the European VOP ecosystem.
Yes. LUXHUB’s VOP Unified Access service is designed to provide a single interface for verifying recipient accounts at payee PSPs across Europe, not just in Luxembourg. LUXHUB maintains direct 1:1 partnerships with relevant domestic and European schemes and hubs, enabling its clients to query VOP services at PSPs in multiple EU member states through a single integration. This pan-European reach is essential for PSPs whose customers make cross-border credit transfers.
LUXHUB’s Payee Verification Platform is specifically designed to reduce the burden of VOP implementation through mutualization. Development, infrastructure, regulatory monitoring, and scheme compliance complexity are shared across all LUXHUB VOP clients. The platform reuses existing technical integrations where possible, making the account list import process easy to implement and maintain. Flexible integration options including single-check, batch-check, and web portal endpoints that allow PSPs to integrate VOP into their existing payment initiation touchpoints with minimal disruption.
24 Financial Institutions in Luxembourg and 10 in Europe, selected LUXHUB as their VOP service provider. This significant mandate reinforces LUXHUB’s position as the leading VOP compliance partner in the Luxembourg market and reflects the confidence of the country’s major financial institutions in LUXHUB’s Payee Verification Platform. Details of the participating institutions are available in the LUXHUB Resource Hub press release from 8 April 2025.
LUXHUB is ISO 27001 certified, the world’s best-known international standard for information security management. In consequence, LUXHUB’s VOP platform stores account holder name and account identifier (IBAN) data submitted by PSPs for verification matching in a secured, full-encrypted, and siloed manner ensuring that one institution’s customer data is protected and strictly isolated from another institution’s data within the mutualized platform.
Furthermore, access to this sensitive information is strictly restricted—no LUXHUB employee can view or retrieve customer data—reinforcing the platform’s robust confidentiality and privacy safeguards. Storage and processing comply with GDPR and financial data protection requirements. The platform is hosted in LUXHUB’s Tier IV Luxembourg data center and also operates under ISO 27001-certified information security management.
LUXHUB has published a dedicated Verification of Payee White Paper ‘Tackling the Verification of Payee Challenge’ covering IPR compliance obligations, EPC VOP Scheme adherence, European PSP connectivity, and implementation guidance. The product brochure can be downloaded here. For a personalised discussion, contact LUXHUB or email info@luxhub.com.
Ready to upgrade your offering?
A 30-minute call with our experts. Let's discuss your current challenges and/or needs. We are excited to talk to you and present our account aggregation and payment initiation solution to your team.
Get started